Goh Peng Ooi and the Silverlake Core-Banking System Built for Regional Scale
Goh Peng Ooi turned banking software into durable infrastructure by combining a reusable core system with patient, institution-by-institution implementation across Asia.
View all stories about this mogul
Goh Peng Ooi built wealth in a part of technology that consumers rarely see and banks cannot casually replace. Core banking software records deposits, accounts, payments, loans, and the rules connecting them. When it works, it disappears beneath daily transactions. When it fails, the institution can stop.
Silverlake’s business grew from that combination of invisibility and consequence. Goh founded the company in 1989 after working at IBM, then expanded through long implementations, regional relationships, and a software architecture intended to be reused across institutions without pretending every bank was identical.
Chapter One: Choosing the System Banks Cannot Pause
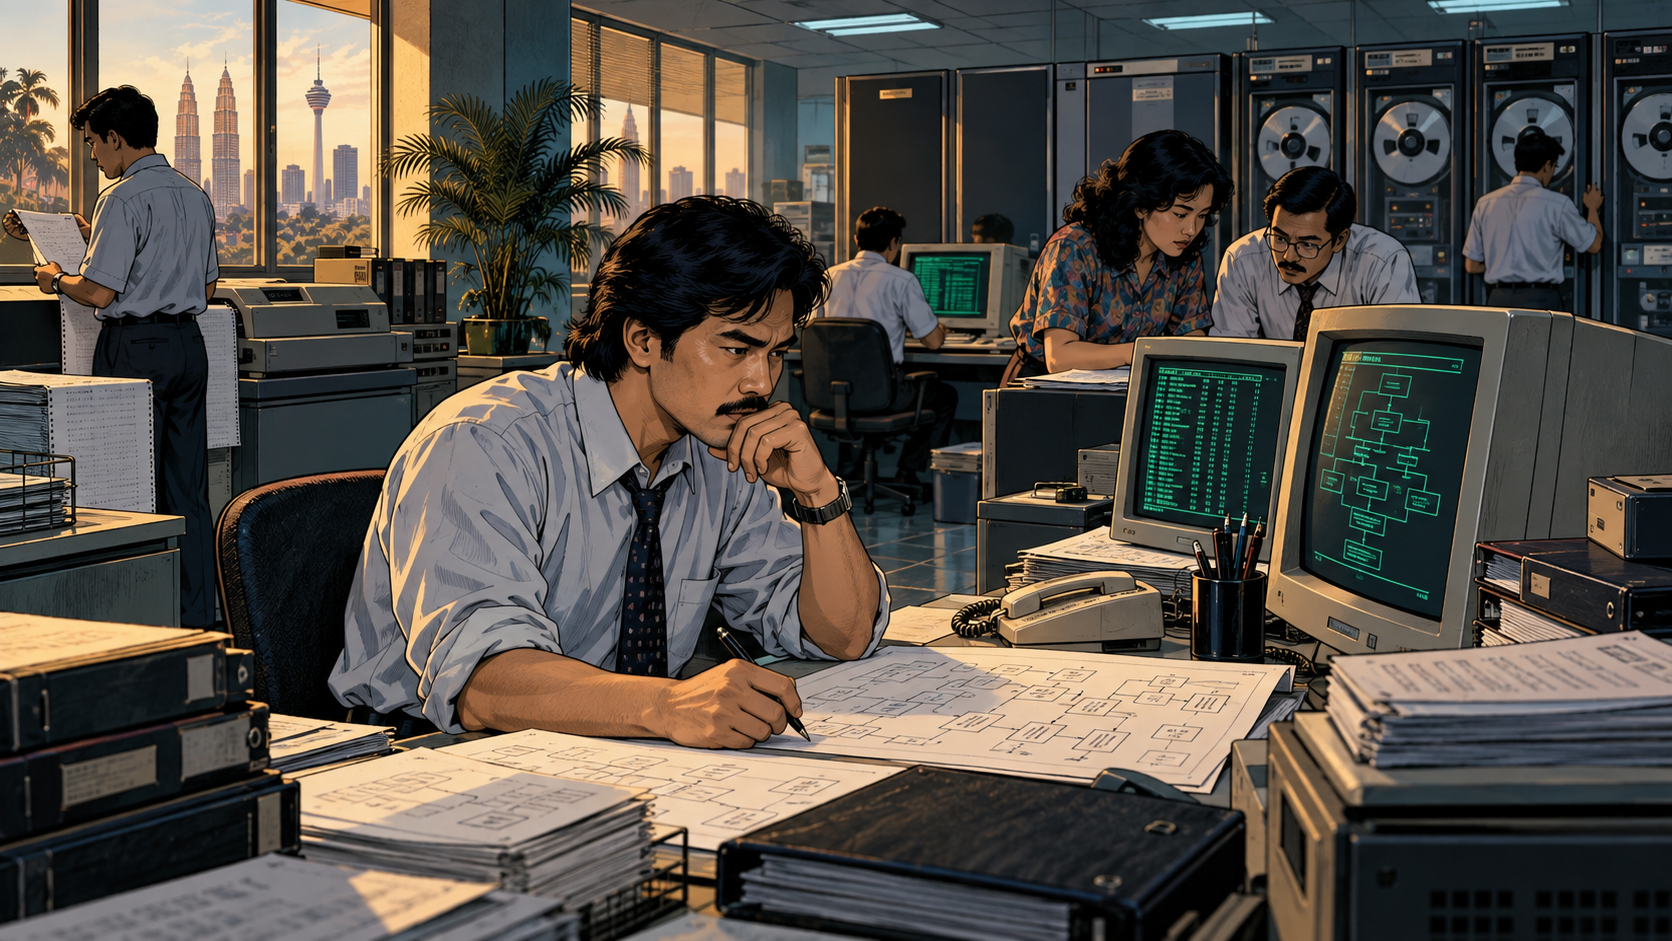
Banking technology in the late 1980s was dominated by large machines, proprietary environments, and institution-specific code. Replacing a core system meant migrating years of records while branches, payments, and customer service continued to operate.
Goh’s IBM background gave him exposure to enterprise computing and the operational expectations of financial institutions. Silverlake did not begin with a consumer interface. It targeted the transactional engine where reliability, reconciliation, and domain knowledge matter more than visual novelty.
This created a demanding sales process. A bank does not buy a core platform because a demo looks modern. It examines references, migration plans, support capacity, regulatory requirements, and whether the vendor will still be present years later.
The same friction becomes a moat after deployment. Once software is embedded in products, branches, reporting, and compliance processes, switching is expensive. Recurring maintenance and enhancement revenue can follow the original implementation, but only if the vendor continues to earn trust.
Chapter Two: Productizing Local Knowledge
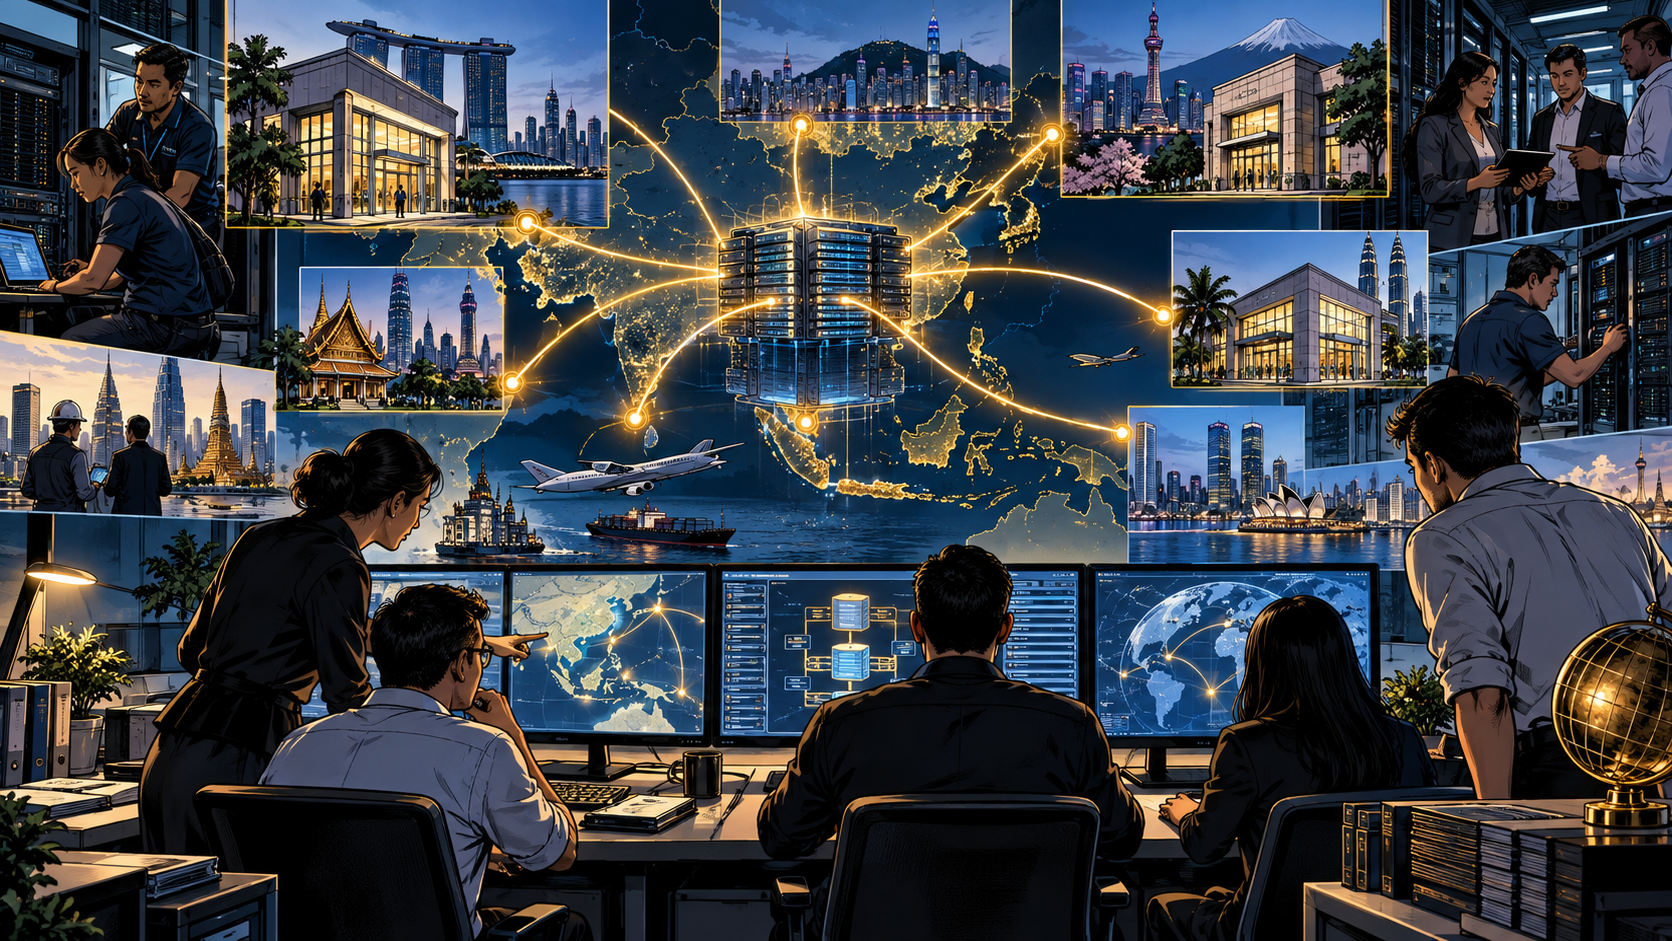
Silverlake’s challenge was to avoid two extremes. Fully custom projects produce revenue but are difficult to scale. A rigid global product may ignore local currencies, regulations, products, and operating practices.
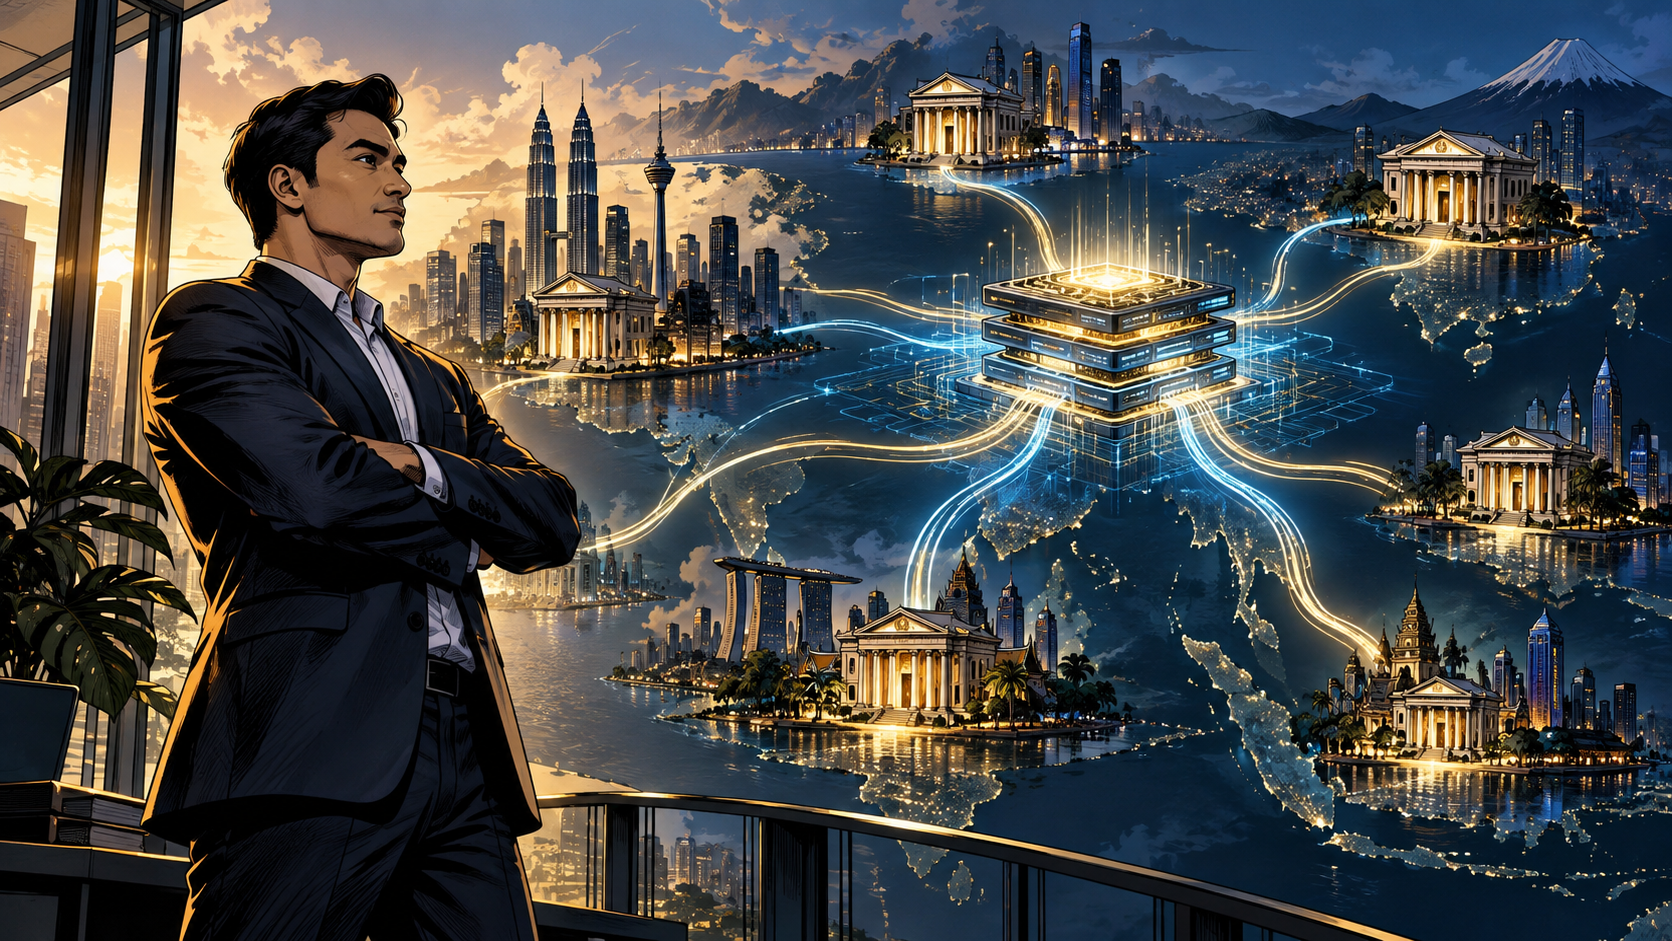
The answer was a reusable core combined with implementation and integration work. Shared components could lower development cost and preserve tested transaction logic. Local configuration and adjacent modules could adapt the system to a particular institution.
This model compounds through references. A successful conversion gives the vendor evidence for the next bank, while implementation experience improves the library of patterns. Regional expansion then becomes less about selling generic software and more about transferring credibility.
Silverlake Axis later broadened into payments, digital channels, insurance, retail, and other enterprise systems. The strategic test for every adjacency was whether it reused customer relationships and domain capabilities. Adding modules simply to enlarge a catalog would increase complexity without strengthening the core.
Chapter Three: Public Markets and Governance Pressure
Silverlake Axis listed in Singapore in 2003, giving the group access to public capital and forcing more of its economics into view. Annual reports documented licensing, project, maintenance, and recurring revenue while shareholders could evaluate margins, concentration, cash flow, and governance.
Founder-led groups often contain private entities, intellectual property arrangements, and related-party transactions built before listing. Those structures may have commercial logic, but public shareholders need clear pricing, ownership, and accountability. Silverlake faced intense scrutiny over its relationships and disclosures, reminding investors that durable software does not remove governance risk.
The company’s investor announcements later documented a voluntary offer and privatization process. A move away from public markets can reduce quarterly pressure and simplify long-term restructuring, but it also removes the continuous disclosure and price discovery that minority shareholders receive from a listing.
The lesson is broader than Silverlake. Enterprise software moats and founder control can coexist, but neither should substitute for transparent governance. The more indispensable a vendor becomes to customers, the more disciplined it must be with shareholders and related entities.
Chapter Four: The Compounding Value of Reliability
Goh’s strategy shows why unglamorous infrastructure can create extraordinary endurance. A consumer app must repeatedly reacquire attention. A core platform earns its position by surviving migrations, regulatory changes, product launches, and years of daily reconciliation.
That endurance does not mean stagnation is safe. Cloud infrastructure, real-time payments, open banking, cybersecurity threats, and new regulatory expectations change what banks require. An incumbent must modernize without breaking the system customers already trust.
Three principles are transferable. First, choose a problem where domain depth matters more than novelty. Second, productize the repeatable portion while preserving implementation skill. Third, treat trust as an operating metric: uptime, reconciliation, security, support, and governance all contribute.
Goh Peng Ooi did not build Silverlake by making banking visible. He built it by making complex transactions reliably ordinary. The balanced verdict is that core-software dependence created a formidable business, while public scrutiny demonstrated that technical reliability and corporate transparency are separate obligations. Great infrastructure companies must deliver both.