Howard Hughes Inherited a Tool Company and Built an Aerospace Empire on a Bet
Howard Hughes turned a $500,000 inheritance into Hughes Aircraft and set a transcontinental speed record in 1937, then bet the company on a 200-ton flying boat.
View all stories about this mogul
In 1925, Howard Hughes inherited 75% of Hughes Tool Company after his father’s death. The company’s dual-cone rock bit had made drilling cheaper, and the royalty stream funded everything that followed. Hughes was nineteen when the inheritance landed, and the terms of his father’s will gave him control outright rather than a trust, a detail that mattered because it meant the money was his to spend on whatever he chose. What he chose, repeatedly, was speed: faster aircraft, faster records, faster routes. The tool company paid for all of it.
The mechanics of that arrangement deserve more attention than they usually get. A rock bit is a consumable. It wears out, gets replaced, and generates another sale, and the dual-cone design made that replacement cycle both cheaper for the driller and more reliable for the supplier. Royalties on a consumable are not a windfall; they are an annuity, and an annuity that grows with every well drilled. That is the crucial difference between Hughes and the aviation pioneers he is often grouped with. Others chased patrons, prize purses, or government contracts, and shaped their designs around what a funder would approve. Hughes already had the funder, and the funder was himself. He could order an aircraft built to answer a question rather than to win a procurement, and he could keep funding it after the question had been answered and the accountants had started to complain.
The Tool Company as Bank
Hughes Tool did not just make Hughes rich. It gave him a private balance sheet. He used its cash to buy a controlling stake in TWA in 1939 and to finance Hughes Aircraft, a division he set up in 1932 at Glendale, California. The structure is worth pausing over, because it explains nearly everything that came later. A public company answers to shareholders and a board; a private one answers to its owner. Hughes Tool’s royalties arrived whether or not Hughes was in the country, whether or not he was paying attention, whether or not his aviation ventures were losing money. That independence let him fund projects that no outside investor would have tolerated, and it let him keep control of them long after a conventional backer would have demanded a say. TWA gave him a platform for his aircraft; Hughes Aircraft gave him a place to build them. Neither would have existed without the drill bit.
There is a second-order effect here that is easy to miss. Because the capital was internal, Hughes never had to justify a project in the language of returns on a timetable. A venture capitalist wants an exit; a board wants a dividend; a government wants a deliverable by a date certain. Hughes wanted the thing to work, and he was willing to let the calendar stretch. That tolerance is what allowed a racer to become a reconnaissance aircraft and a reconnaissance aircraft to become a wooden flying boat, each step absorbing the lessons and the losses of the one before. The cost of that freedom was that no outside discipline ever told him when to stop, which is precisely how a project can outlive the problem it was built to solve.
Records Before Revenue
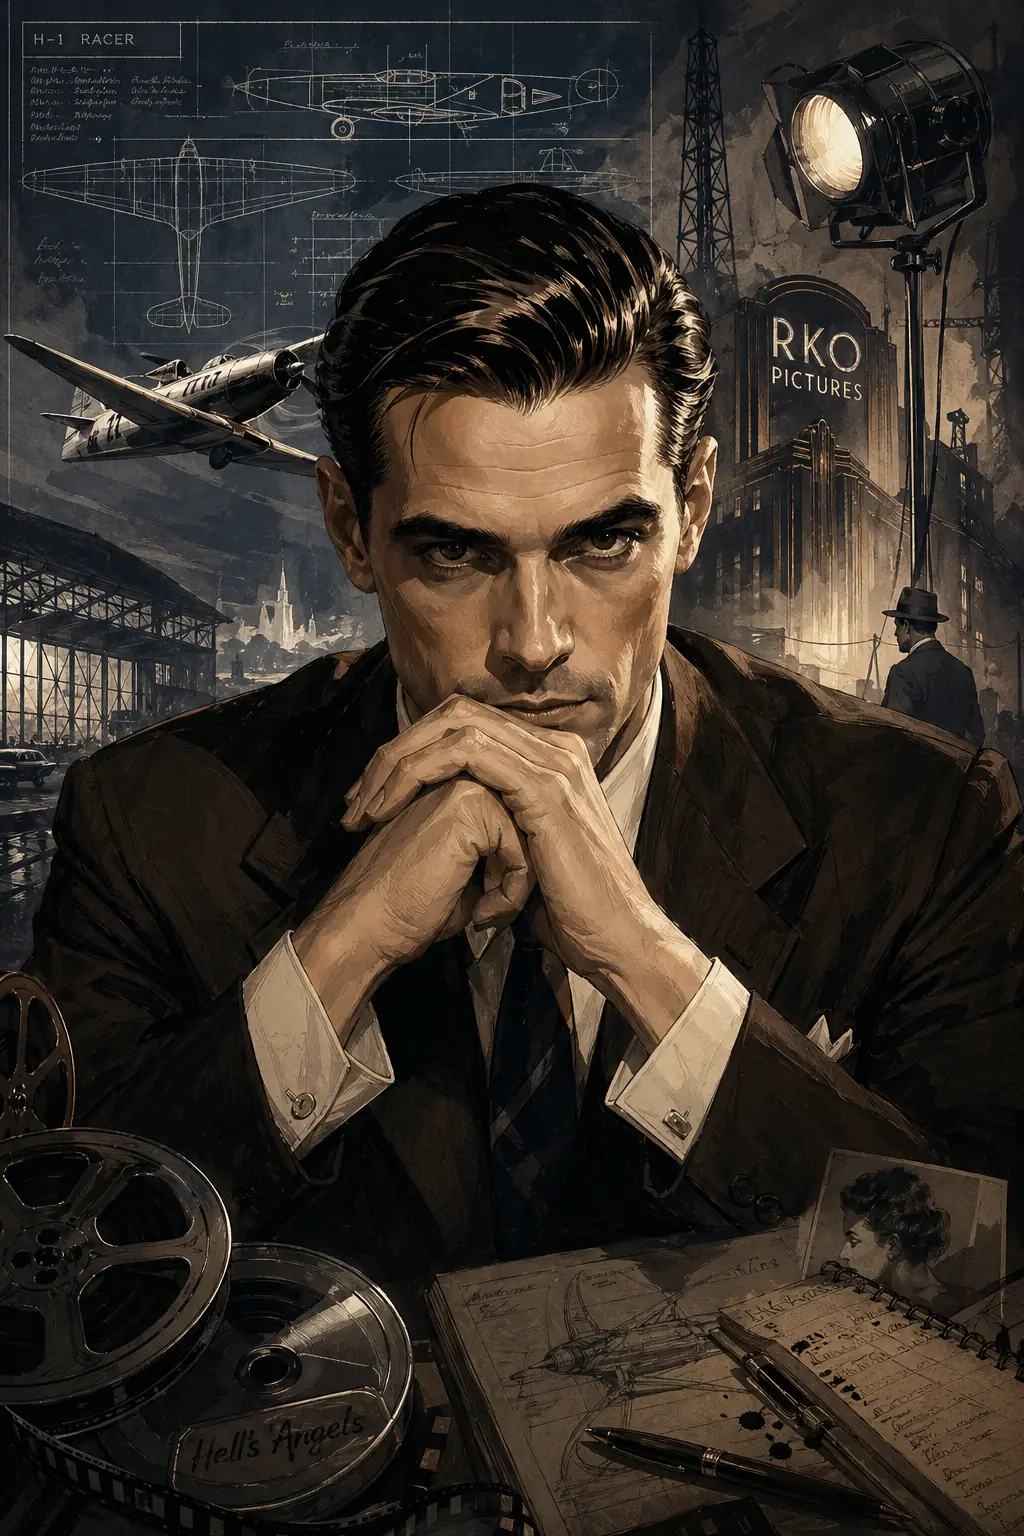
Hughes hired engineers rather than managers. In 1935, his H-1 racer set a landplane speed record of 352 mph. In 1937, he flew a Lockheed 14 around the world in 3 days, 19 hours, and 8 minutes. In 1938, he flew a similar route in 91 hours, cutting the previous record nearly in half. The sequence matters: the H-1 was a design exercise that proved what streamlined shapes and powerful engines could do, and the Lockheed flights were demonstrations that the same principles could be applied to practical travel. Hughes was not merely chasing trophies. Each record was a public argument that aviation was ready for passengers and cargo, and the argument served TWA’s interests as much as his own vanity. The engineers he hired learned by building racers, and what they learned went into the aircraft the company later sold.
The H-1 itself is the clearest illustration of how the money converted into knowledge. It was a short-range machine built around a powerful engine and an extremely clean airframe, and its record was less a product of brute horsepower than of drag reduction—flush riveting, retractable gear, and a shape refined in wind tunnels rather than in a styling office. Those are exactly the concerns that matter to an airliner, where fuel burn and speed determine whether a route pays. The round-the-world flights made the same point in a form the public could understand: a trip that had taken weeks was now measured in days, and the aircraft that did it was a stock Lockheed rather than a one-off. Hughes was demonstrating that the frontier had moved from what was possible to what was practical, and TWA was positioned to sell the practicality.
It is worth noting what the records did not do. They did not, by themselves, make money. A racer carries no passengers, and a record flight is a cost center dressed as publicity. The value was indirect: the engineering data, the trained staff, and the public association between the Hughes name and speed. That association was an asset TWA could trade on, and it was an asset Hughes could use to attract the engineers who would later build military aircraft. The records were, in effect, research and development conducted in public, with the bill paid by the tool company and the benefit accruing to the aviation division.
The Wartime Pivot
Hughes Aircraft’s first military contract came in 1942 for the D-2 dive bomber, which never entered full production. The company’s real wartime work was the Hughes XF-11 reconnaissance aircraft and, later, the Hughes H-4 Hercules—the Spruce Goose—a wooden flying boat funded by the U.S. government to move troops without using aluminum. The D-2’s failure is instructive rather than embarrassing: it shows that the company’s strength was not in mass-producing proven designs but in pushing ambitious ones. The XF-11 was a fast, long-range reconnaissance platform built around the same instincts that had produced the racers, and the Hercules was an attempt to solve a wartime shortage of aluminum by building an aircraft out of wood. Both were bets on engineering rather than on procurement, and both carried the risk that comes with that.
The wartime context explains why those bets looked reasonable at the time. Aluminum was a strategic material, and every pound of it that went into an airframe was a pound that could not go into another bomber. Wood, by contrast, was abundant, and the boat-building industry already knew how to work it. The Hercules was therefore not a whimsy but a supply-chain argument: build the airlifter out of a material that is not scarce. The same logic that made the dual-cone bit valuable—solve the constraint that costs the customer the most—was being applied to aircraft. What the argument missed was that the constraint would relax before the aircraft was finished.
The XF-11 carried a different kind of risk. It was a fast, long-range reconnaissance platform, which meant it was optimized for speed and altitude rather than for payload or producibility, and it was built around the same instincts that had produced the racers. That is a strength in a design study and a liability in a procurement program, because the military buys fleets, not prototypes, and a fleet demands maintainability, parts commonality, and a predictable schedule. The D-2’s failure had already shown that the company’s strength was not in mass-producing proven designs but in pushing ambitious ones. The pattern that would define Hughes Aircraft for decades was set in these years: it won on capability and lost on cadence.
The Bet That Became a Myth
The Hercules flew once, on November 2, 1947, for about a minute at 70 feet. It never flew again. The project cost $23 million in government money and $18 million of Hughes’s own. By then Hughes had already sold his TWA stake in 1966 for $546 million. The single flight is often remembered as a failure, but the arithmetic tells a more complicated story. The aircraft did what it was built to do—it lifted off—and the reason it never flew again was not that it could not but that the war it was designed for had ended and the need for a wooden troop carrier had passed. The government money and Hughes’s own money were spent on a capability that arrived too late to be used. The TWA sale, meanwhile, came nearly two decades after the flight, which means Hughes held the airline through the entire period in which the Hercules was being built and defended. The $546 million exit was the payoff on the 1939 purchase, and it dwarfed the $18 million he had put into the flying boat.
That timeline is the part most retellings omit. The Hercules is usually presented as the end of a story, the moment the eccentric billionaire overreached. In fact it was a middle chapter, and the enterprise that funded it was still running. Holding TWA through those two decades was itself a bet—on routes, on jets, on regulation—and it was a bet made with the same balance sheet that was paying for the flying boat. The $18 million of Hughes’s own money was not the whole exposure; the opportunity cost was the capital tied up in an aircraft that never entered service. The $546 million exit is the measure of what the airline was worth when he finally let it go, and it is the number that makes the flying boat’s losses look small.
The counter-evidence to the failure narrative is straightforward. The aircraft lifted off, which is the one thing a flying boat must do. It was grounded by circumstance rather than by defect, and the circumstance was the end of the war and the arrival of the aluminum supply that the wooden design had been built to work around. A critic could reasonably answer that a capability that arrives too late is, in practical terms, a failure regardless of why, and that the government’s $23 million bought a demonstration rather than an airlifter. Both readings are defensible, and the honest conclusion is that the Hercules was a successful experiment and an unsuccessful product. The distinction matters because it is the same distinction that separates Hughes Aircraft’s racers from its contracts.
What Survived
Hughes Aircraft became a defense and satellite contractor; it was acquired by Raytheon in 1997 for $9.5 billion. Hughes Tool was sold to Baker International in 1987. The fortune that began with a drill bit ended in a holding company, but the aerospace division outlasted its founder’s legend. The pattern is consistent: the tool company supplied the capital, the aircraft company supplied the engineering, and the legend supplied the publicity. What endured was not the Spruce Goose, which sits in a museum, but the satellite and defense work that grew out of the same division. For the reader, the lesson is less about Hughes than about structure. A private cash engine let one man fund decades of speculative engineering, and the returns came not from the bets that became famous but from the ones that became businesses.
The satellite and defense work is the part of the story that rarely makes the documentaries, and it is the part that paid. It grew out of the same division, the same engineers, and the same willingness to build things that had no obvious customer yet. The difference is that a defense or satellite contract comes with a customer built in, which imposes the discipline the racers never had. That is the real lesson for anyone running a speculative enterprise: the freedom to fund your own experiments is valuable only if some of them eventually acquire a customer who will pay for the result. Hughes had both halves—the private cash engine and, eventually, the public contracts—and the fortune survived because the second half outlasted the first.
There is a caution in the same pattern. The tool company was sold in 1987 and the aerospace division in 1997, and what remained was a holding company rather than an operating business. The legend outlived the machinery. A reader tempted to imitate Hughes should notice that the structure, not the personality, did the work: a consumable product with recurring royalties, a private owner with unchecked control, and a long horizon that no shareholder meeting could shorten. Those are reproducible conditions. The eccentricity is optional.
💡 Key Insights
- ▸ Hughes Tool Company provided the cash flow that financed Hughes Aircraft and TWA.
- ▸ Hughes set speed and circumnavigation records before his companies sold a commercial product.
- ▸ The Spruce Goose flew once and consumed $41 million in public and private funds.
- ▸ Hughes Aircraft outlived its founder and was sold to Raytheon for $9.5 billion in 1997.