Patrick Collison: How Stripe Built the Financial Rails of the Internet Economy
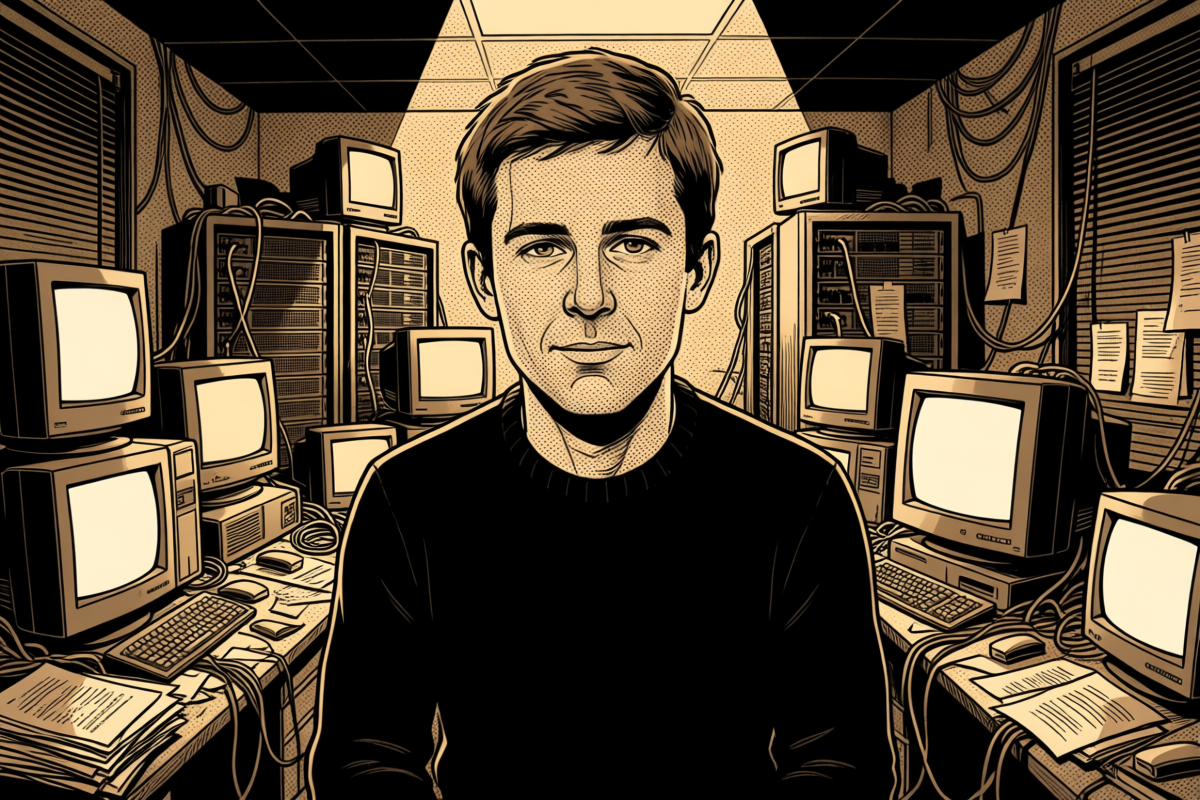
Two brothers built the plumbing for internet payments without ever chasing the spotlight, and in doing so set the toll rate for a generation of online business.
View all stories about this mogul
Patrick Collison: How Stripe Built the Financial Rails of the Internet Economy
When Patrick Collison and his brother John founded Stripe in 2010, moving money on the internet was a bureaucratic nightmare. Developers who wanted to accept payments had to navigate a maze of merchant accounts, gateways, and legacy banks that treated the web as an afterthought. The Collisons bet that the internet would become the primary venue for commerce and that the infrastructure underneath it needed to be rebuilt from first principles. That bet turned Stripe into one of the most valuable private companies in the world and made Patrick Collison one of the most closely watched founders of his generation.
From Limerick to the Frontier
Patrick Collison grew up in County Limerick, Ireland, the son of an engineer and a microbiologist. He was a prodigy in the literal sense: he entered the University of Limerick at sixteen, competed in international science competitions, and by his late teens had already founded a company. That first venture, an auction site called Shuppa, later merged into Auctomatic, which the brothers sold in 2008 for a reported several million dollars. The exit was modest by Silicon Valley standards, but it gave the Collisons something more valuable than capital: proof that they could identify a gap and build against it.
Patrick spent a brief stint at MIT before returning to the startup world, and the experience sharpened a conviction that would define his career. The most important layer of the internet economy was payments, and it was the layer most resistant to change.
That resistance was not accidental. Payments sit at the intersection of several deeply entrenched systems: card networks with decades of rules, acquiring banks that carry the credit risk, processors that translate between message formats, and regulators in every jurisdiction who treat money movement as a matter of public trust. Each layer had its own incentives, its own timelines, and its own reasons to move slowly. For a developer in 2009, the practical experience of accepting a payment was often weeks of paperwork, a stack of gateway documentation, and a merchant account approval process that could stall on a single mismatched address. The Collisons’ early insight was that this friction was not a law of nature. It was an artifact of systems designed before the web existed, and artifacts can be rebuilt.
Understanding why those systems were so resistant requires a brief look at what each layer actually does. Card networks set the rules of the road: interchange rates, chargeback procedures, and the liability shifts that determine who eats a fraudulent transaction. Acquiring banks sponsor merchants into those networks and absorb the credit risk if a merchant fails. Processors translate between the many message formats that different institutions use, and regulators in every jurisdiction treat money movement as a matter of public trust, which means licensing, capital requirements, and consumer-protection rules that vary from country to country. None of these layers was designed to talk to the others in real time, and none had an incentive to make a developer’s life easier. The friction was structural, and that is precisely why it persisted.
The Insight Behind Stripe
The founding insight was deceptively simple. Accepting money online was not a technology problem; it was an integration problem. Banks had built their systems for a world of physical branches and paper signatures, and the tools available to developers were brittle, opaque, and slow to set up. Stripe’s answer was to abstract the complexity away. A developer could drop a few lines of code into a website and start accepting payments within minutes, with the company handling the fraud, compliance, and bank relationships behind the scenes.
That focus on the developer as the customer was a strategic masterstroke. By making integration effortless, Stripe spread virally through the startups and platforms that were building the next generation of internet businesses. What began as a tool for small developers became the default payment layer for an entire ecosystem, from e-commerce startups to subscription software to marketplaces. The company expanded from payments into billing, fraud prevention, corporate cards, and treasury services, each addition deepening its position as the financial operating system for online businesses.
The mechanism behind that expansion is worth unpacking, because it explains why Stripe’s position proved so durable. Each product the company added was adjacent to a problem its existing customers already had. A startup that accepted payments soon needed subscription billing; a marketplace that onboarded sellers soon needed identity verification and payouts; a company with revenue soon needed a way to hold and move its own cash. Because Stripe already sat inside the transaction flow, it could offer those services without asking customers to integrate a new vendor. The result was a compounding advantage: every new product increased switching costs, and every new customer generated data that improved fraud detection and authorization rates across the network. That flywheel is the real explanation for how a payments API became an operating system.
There is a second mechanism at work that is easy to miss: the developer relationship itself. Once a company’s engineers have built against an API, the cost of ripping it out is measured not just in dollars but in engineering hours, retraining, and the risk of breaking something that works. Stripe’s documentation, test tooling, and client libraries were designed to make the first integration trivial and every subsequent one familiar. That is a deliberate strategy, and it is why the company’s early lead compounded rather than eroded.
Building the Rails, Not Just the On-Ramp
The phrase “financial rails of the internet” is often used loosely, but Stripe’s trajectory illustrates what it means. The company did not merely process transactions; it built the connective tissue that lets money move between businesses, platforms, and countries with a reliability that legacy infrastructure could not match. That required patient, unglamorous work: negotiating with regulators, building relationships with banks across dozens of markets, and investing heavily in fraud detection and reliability engineering.
Patrick Collison’s public persona reflects that seriousness. He is known for a restless intellectual curiosity, publishing long reading lists, funding scientific research through philanthropic vehicles, and engaging with questions far beyond payments. He has argued that progress in science and technology has slowed and that the institutions supporting it need reform. That temperament, equal parts engineer and institution-builder, shaped Stripe’s culture: a company that treats infrastructure as a long-term public good rather than a quick arbitrage.
That stance carries a cost as well as a benefit. Treating infrastructure as a public good means accepting slower payoffs, heavier compliance burdens, and a willingness to be boring in public. It also means that when the company stumbles, the scrutiny is sharper, because the stakes are other people’s money. Stripe’s reliability requirements are not abstract: an outage during a holiday shopping window is not an inconvenience but a direct revenue loss for every business on the platform. The engineering culture that Collison cultivated reflects that reality, with an emphasis on correctness, observability, and gradual rollouts that is closer to aerospace than to consumer software.
That aerospace analogy is more than rhetorical. Payment systems have to be correct under adversarial conditions, with partial failures, retries, and duplicate requests that can silently double-charge a customer if the logic is wrong. The discipline of designing for those edge cases, of testing failure modes rather than just happy paths, is what separates a payments company from a website. It is also why the work is slow to build and hard to copy.
The Valuation and the Scrutiny
Stripe’s rise made it a symbol of the internet economy’s financial plumbing. Its valuation soared into the tens of billions during successive funding rounds, and the company became a bellwether for the health of the broader startup ecosystem. When the market turned in 2022, Stripe’s valuation was cut, a correction that mirrored the broader reset across technology. The episode was instructive: even a company built on durable fundamentals was not immune to the cycle, and the Collisons responded by emphasizing profitability and discipline rather than growth at any cost.
That pivot said something about the maturity of the business. Stripe had grown from a scrappy startup into a company with thousands of employees, global operations, and the kind of regulatory exposure that comes with touching money at scale. Patrick Collison’s challenge shifted from proving the concept to stewarding an institution.
The correction also invited a fair counter-argument. Skeptics noted that Stripe’s valuation had been set in a period of cheap capital, and that a payments business, however essential, is still exposed to the volume of commerce flowing through it. If online spending slows, so does Stripe’s revenue, and the company’s expansion into adjacent products does not fully insulate it from that cycle. The Collisons’ response, emphasizing profitability, was in part an acknowledgment of that exposure. But the deeper point stands: the correction tested the company’s discipline without testing its premise. Businesses still needed to move money online, and the rails still needed to work. The valuation was a measure of sentiment; the transaction volume was a measure of dependence.
There is a further nuance worth holding onto. A payments business earns a small slice of every transaction, which means its fortunes are tied to the gross volume flowing through it rather than to any single customer. That structure is resilient in one sense, because it is diversified across thousands of merchants, and fragile in another, because it concentrates exposure to the health of online commerce as a whole. The 2022 correction was a reminder that even infrastructure is not a hedge against the cycle; it is a leveraged bet on the layer it serves.
The Legacy So Far
Patrick Collison’s story is often told as a prodigy’s ascent, but the more useful lesson is about choosing the right problem. The Collisons did not build a consumer app or chase a viral trend. They picked the layer of the internet economy that was hardest to change and most essential to everything else, then committed to fixing it with engineering discipline and patience. The result is a company that quietly underpins a vast share of online commerce.
For the reader, the practical implication is subtler than a founder biography. Every time a checkout page loads without a hitch, a subscription renews without a failed charge, or a marketplace pays a seller in another country, some of that invisible labor is the kind of infrastructure Collison argued for. The lesson is not that every founder should build payments rails. It is that the most durable businesses often sit underneath the visible layer, solving problems that customers never think about because the solution works. Choosing that layer requires patience, because the rewards arrive slowly and the work is unglamorous. But it also confers a kind of staying power that consumer trends rarely do.
That staying power has a cost the biographies rarely dwell on. Building underneath the visible layer means accepting that your customers will never love you the way they love a consumer brand; they will simply depend on you, and dependence is a colder and more durable form of loyalty. It also means that the company’s reputation is tied to events it cannot fully control, from card network rule changes to central bank policy to the spending habits of shoppers in markets it has only just entered. Collison’s institution-building temperament is well suited to that reality, but it is a harder path than the one most founders are sold.
Whether Stripe remains independent, goes public, or evolves into something else entirely, its influence is already baked into the infrastructure of the internet economy. Patrick Collison helped build the rails that carry the money. For a founder still in his thirties, that is a remarkable foundation, and the story of what he builds next is one the industry will keep watching.